
Quant Factor Investing: Core Logic, Neutralization, and Alpha
In the world of investing, everyone seeks companies poised for sustained growth. It’s like identifying the "top students" among thousands who will eventually gain admission to Tsinghua or Peking University. But what are the criteria? Is it high grades? Rapid improvement? Or physical stature?
In quantitative investing, we employ a systematic method to "health-check" stocks. The core of this method lies in the first piece of jargon we are demystifying today: factor. One could say that the history of modern quantitative investing is the history of continuously discovering, defining, and applying various factors.
We will start with the core concept of "factor," dissecting the concepts of factors, factor values, factor exposure, factor portfolios, and factor returns.
What Is a Factor?
When judging the nutritional value of food, we typically look at substances and their contents: proteins, carbohydrates, fats, vitamins, and so on. If a food is rich in these nutrients, we classify it as highly nutritious. Here, proteins and vitamins are the "factors" constituting the judgment of nutritional value.
Stock returns operate similarly. Factors are the fundamental drivers that systematically explain the sources of stock returns. They act like a nutritional label for stock returns, precisely decomposing a stock’s long-term performance into a combination of contributions from different factors.
For a characteristic to stand out from thousands of possibilities and become a trustworthy "factor," it must meet five critical, core conditions. These five conditions are indispensable and collectively form the cornerstone of professional factor investing.
First, it must withstand the test of time, known as Persistence. A true factor cannot be effective only during a short, favorable period in the past. It must traverse decades of history, proving its value through bull and bear markets, economic recessions, and booms.
Second, its influence must be broad, known as Pervasiveness. A powerful factor’s effectiveness cannot be limited to a single country or specific market. It should act as a universal law, demonstrating its power across US stocks, China A-shares, European and Japanese markets, and even across asset classes like bonds and commodities. For instance, factors from the Alpha101 dataset, though developed for the US market, remain applicable to China A-shares after localization.
Third, its definition must be robust, known as Robustness. A factor’s definition must be sturdy, not overly fragile or precise. For example, if we want to buy cheap stocks, the value factor should remain effective whether defined by Price-to-Earnings (P/E), Price-to-Book (P/B), or Price-to-Sales (P/S) ratios. The conclusion should be largely consistent regardless of the specific metric used.
Fourth, it must be investable, known as Investability. After accounting for real-world factors like transaction costs and liquidity, investors must be able to practically capture the returns generated by this factor through portfolio construction. A factor that exists theoretically but has transaction costs too high to profit from has no practical value.
Finally, and most fundamentally, it must have a hard-core logic, meaning an intuitive Economic Explanation. For a factor to generate long-term profits, there must be a convincing economic story behind it. You must be able to explain clearly what you are earning: Is it risk compensation for bearing risks others dare not take? Or is it a cognitive dividend derived from exploiting common irrational behaviors in the market (such as chasing trends)?
Only by meeting these requirements can an ordinary characteristic be promoted to a factor worthy of our trust.
Now that we have factors, we must also know their respective "contents," i.e., their numerical values. How do we measure these magnitudes?
Finding Proxy Variables to Obtain Factor Values and Factor Exposure
For factors, we cannot measure them directly, but we can find proxy variables (Proxy). For example, we can use financial indicators such as Price-to-Earnings (P/E), Price-to-Book (P/B), and dividend yield to represent the value factor. These indicators allow us to calculate specific numerical values, which are called factor values.
For instance, if Stock A has a P/E of 10 and Stock B has a total market capitalization of 200 billion, then 10 is the factor value for P/E, and 200 billion is the factor value for market capitalization. Through this method, we can calculate the respective factor values for each stock across different factors.
Suppose you want to use the P/E ratio to identify the most undervalued stocks in the entire China A-share market. A natural idea would be to rank all companies from lowest to highest P/E and buy the lowest portion. However, this approach contains a fatal logical flaw from the start. The so-called "undervalued" stocks you select would overwhelmingly concentrate in industries with naturally low valuations, such as banking, real estate, and construction.
Because P/E ratios vary drastically across different industries. Bank stocks typically have P/E ratios of 5-10, while semiconductor stocks might range from 30-50. Directly comparing a bank stock with a P/E of 10 to a semiconductor stock with a P/E of 50 to see which is "cheaper" is inherently unfair.
Simply ranking them means your portfolio appears to be betting on the value factor, but in reality, you are inadvertently taking a heavy position in specific industry factors. Your value factor has been "contaminated" by strong industry characteristics.
Therefore, to solve this "apples vs. oranges" comparison problem, we introduce sector neutralization. First, stocks are grouped by industry, and residuals are obtained via linear regression. Statistically, this residual represents the part of the original factor that cannot be explained by industry factors. This eliminates the natural valuation differences between industries, yielding the factor value for that stock after sector neutralization.
Beyond industry factors, we must also guard against another powerful noise: market capitalization. The logic here is similar to sector neutralization, but the root cause differs. The root cause is that many "good company" traits we pursue, such as "high quality" measured by ROE, naturally favor large companies. This is almost inevitable: giants possess wide moats, mature business models, and stable profitability, keeping ROE high year-round. Most small companies are still growing wildly, facing a "survival of the fittest" scenario, so their ROE performance is naturally unstable.
Thus, when you screen for "high ROE," your stock selection pool inevitably tilts toward large-cap stocks. Your "quality factor" is contaminated again, this time by the "market-cap factor."
To separate these two effects, market-cap neutralization (Size Neutralization) was born. It is usually accomplished through regression analysis. Note that before performing regression analysis, we need to take the logarithm of the market-cap factor.
After processing through market-cap neutralization and sector neutralization, we truly possess a unified tool to evaluate and compare the strength of all stocks across any factor. This standardized score after processing is called factor exposure. It measures the degree to which a stock conforms to a specific factor’s characteristics. Higher exposure indicates the stock is closer to the factor’s definition.
Neutralization Is Not a Golden Rule
In practical application, neutralization, especially sector neutralization, is highly controversial in the industry and is not a mandatory golden rule.
The effectiveness of sector neutralization faces two problems:
First is the issue of industry classification. How do you tag a company with an "industry" label?
Many companies have diversified businesses, and their operations transform. A company that previously focused on real estate may now transition into high-tech. Is the industry classification standard dynamic or static? Different data providers offer different standards. If this foundation is unstable, the effectiveness of sector neutralization must be questioned.
Second is the issue of statistical口径 (caliber) for fundamental data.
In the China market, due to the evolution of accounting standards, the "net profit" we see today may have vastly different calculation methods and connotations compared to the "net profit" from ten years ago, despite having the same name. Performing fine-grained neutralization on data that is not fully consistent over time naturally faces challenges.
The reality is that the majority of public backtests default to no market-cap neutralization. Why? Because "small market cap" itself is a profitable factor. Many strategies’ backtest returns naturally include the dividend of the "small-cap effect." If you strip this part away, the backtest curve may not look as good.
Capturing and Testing Factor Returns
After market-cap and sector neutralization, we obtain the factor exposure score. We can then screen for candidates meeting our specific requirements from thousands of stocks at each moment $t$, thereby constructing a factor portfolio (Factor Portfolio).
The most classic method is the ranking and grouping method:
- Ranking: Rank all stocks in the market from highest to lowest based on their exposure to a specific factor.
- Grouping: Divide the ranked stocks into $N$ equal groups, for example, 10 groups. The first group contains stocks with the highest value factor exposure, and the tenth group contains those with the lowest exposure.
After grouping, we can calculate its factor return (Factor Return).
Factor return measures the pure return driven solely by the factor itself, independent of the overall market’s rise or fall. How do we obtain this pure return? The answer is constructing a long-short portfolio (Long-Short Portfolio). The daily return rate of this constructed "long-short portfolio" is the factor’s factor return.
The specific method is:
- Buy an equal-weighted portfolio of stocks with the highest factor exposure (Long)
- Sell short an equal-weighted portfolio of stocks with the lowest factor exposure (Short)
Its core lies in risk hedging, similar to market-neutral strategies. Assume the overall market rises by 1% today. Our long portfolio benefits, but our short portfolio loses. Since the capital invested in both long and short ends is equal, the impact of the overall market’s rise or fall on the portfolio’s net value largely cancels out. This portfolio’s Beta is close to 0, achieving market neutrality (Market Neutral).
After hedging out the market impact, the final return of this portfolio comes almost entirely from the relative performance between the long and short portfolios. If the portfolio generates a positive return, it must be because our long "cheap stocks" outperformed our short "expensive stocks." This excess return is driven by the differences in factor attributes.
Connecting the daily factor returns forms a factor return curve. By analyzing its long-term performance, we can objectively judge whether a factor has been effective over history.
Daily Campus
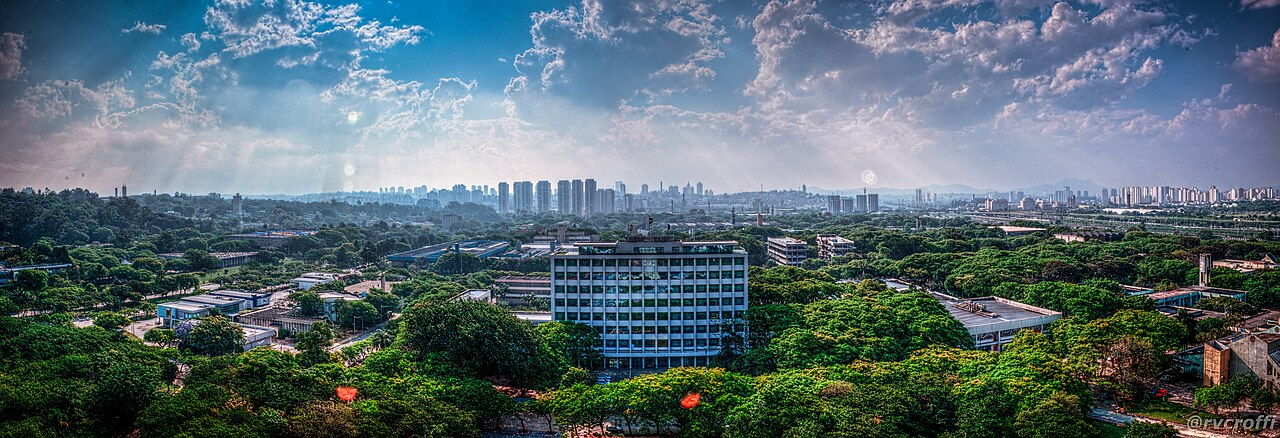
Today’s cover image is from a university in South America. Do you know which university this is?
It is one of the top institutions in Latin America. Interestingly, the "quantitative gene" of the country’s top hedge fund industry largely originates from this university. For example, Luis Stuhlberger, hailed as the "xx Soros," graduated from the university’s Institute of Technology (Engineering Department).
In this country, many top hedge fund managers are not finance majors but alumni of this university (the one we are guessing today), possessing deep backgrounds in mathematics and engineering like Stuhlberger.
Leveraging strong mathematical logic and risk control capabilities, they apply complex factor models to Latin America’s volatile markets, creating astonishing long-term returns. This precisely confirms what we stated in the article: Behind factors, there must be hard-core logic.
Participate in today’s vote to see if the Six Degrees of Separation theory can help us link to this xx Soros.