
Wang Yiping: Why Logic Beats Black-Box ML in Quant
Wang Yiping, founder of Evolutionary Assets, is a private equity practitioner who demonstrated investment talent from a young age.
Starting with his father’s securities account at age 14, he initially profited from value investing, almost by accident. Notably, he does not come from a prestigious university background. He earned his bachelor’s degree in International Finance from Jiangxi University of Finance and Economics (JUFE), won first place in the national university student financial investment simulation trading competition (equity group) in his junior year, and was admitted to the master’s program in Financial Engineering at the same university.
During his master’s studies, he secured 100,000 RMB in startup capital from his parents. Through index arbitrage between Hong Kong and China A-shares, he multiplied his principal 50 times by the time he graduated.
In 2014, he founded Evolutionary Assets, officially entering the private equity sector. Before 2016, he primarily engaged in subjective investing. Starting in 2016, he experimented with a hybrid subjective-plus-quantitative approach. By the end of 2021, he decided to fully transition to “logic-driven quantitative investing.”
Therefore, this article interprets a deep-dive interview with Mr. Wang Yiping, published by Securities China in April 2025, titled “Persisting in Hand-Crafted Factors: Doing Logic-Driven Quantitative Investing.” Thanks to this insightful interview, we can now explore how Mr. Wang successfully transitioned from subjective to quantitative investing and what he means by “logic-driven quantitative investing.”
What Are Logic-Driven Factors? Are They Subjective?
Mr. Wang Yiping answers this question as follows.
Logic-driven factors are rooted in the first principles of investment and the underlying operational laws of the market. Essentially, they represent a deep accumulation of human cognitive insight into the market, with core value lying in compensating for the shortcomings of traditional quantitative models in handling small-sample extreme events.
The core logic of the stock market is that “prices fluctuate around value, and excessive deviations will eventually mean-revert.” However, statistical quantitative models focused on short-to-medium-term returns often lack this underlying cognitive foundation. For example, in early 2024, when micro-cap stocks faced inflated valuations followed by liquidity drying up, experienced investors would avoid them, but quantitative models might blindly buy the dip based on short-term oversold signals, suffering heavy losses.
Although such extreme scenarios are rare in history and lack statistical significance, they can be fatal to a strategy. Investing is not merely a numbers game; the stock market is a mirror of the real economy, filled with sudden variables yet governed by inherent laws. Ignoring these essences makes strategies fragile, even prone to collapse. Therefore, we must embed underlying principles like “price moves around value” into models to establish a safety底线 (bottom line) for quantitative decision-making.
If you read our previous issue, you might feel a sense of clarity now.
The logic-driven factors mentioned here are essentially the a priori factors from Luoshu Investment’s previous article. Both refer to theory-driven alpha models.
In this interview, Mr. Wang Yiping also expanded on the practical advantages of logic-driven factors and the limitations of data-driven alpha models.
Mr. Wang stated that Evolutionary Assets’ ability to effectively control drawdowns during the sharp declines in micro-cap stocks in February, April, and June 2024 was primarily due to the long-tail factors within their logic-driven factor set. These factors timely prevented the model from buying the dip in small-cap stocks.
Statistical factors argue that since small caps performed well in the past and have now dropped sharply, it is time to buy the dip. Logic-driven factors, however, argue that small caps have lost liquidity and should be avoided. While the two camps hold different views, logic-driven factors possess a “veto power.”
Regarding why he decided to pursue logic-driven quantitative investing, Mr. Wang explained that their quantitative strategies initially performed well, but began to gradually fail in 2019. The problem lay in over-reliance on machine learning. At that time, the vast majority of their factors were automatically derived by machines, following a path of imitation learning—a black box process.
Moreover, the sheer number of factors made them impossible to review comprehensively. When performance issues arose, timely and effective attribution was impossible. Thus, Mr. Wang pointed out that the difficulty in attribution and achieving true innovation are key problems with machine learning. Consequently, they removed all machine-learning-generated factors and returned to the original hand-crafted, logic-based factors.
However, Mr. Wang also noted that model stability stems from diversity; statistical factors and logic-driven factors are equally critical. Human top-down deductive reasoning and machine bottom-up sample induction are complementary perspectives. Combining induction and deduction is a more scientific methodology.
Educational Path from Subjective to Quantitative
As mentioned at the beginning, Mr. Wang Yiping started with subjective investing. When asked what he did during the initial phase of transitioning from subjective to quantitative investing, his learning path serves as a reference for anyone seeking to make a similar transition.
He spent one year reading over 200 domestic and international papers, establishing a broad understanding of the overall architecture and practice of quantitative investing. During this period, he studied 13–14 hours daily, with no days off.
However, he believes there is a significant gap between theory and practice; we cannot simply copy overseas experiences. When constructing factors, while referencing methods from overseas papers, he combines them with the characteristics of the China A-share market to localize certain common factors. He also derives some unique factors through analogical reasoning during his research.
Mr. Wang also mentioned the famous paper “Alpha101,” which discusses inputting data end-to-end to allow machines to output statistically valid factors. Referencing this method, they used their developed basic factors as a base, allowing machines to derive thousands of factors to run models.
Alpha101
Here is a brief introduction to Alpha101 and “end-to-end.”
Alpha101 refers to 101 price-volume factors publicly released by WorldQuant in 2015, which can be directly used in quantitative strategies. These factors are essentially statistical patterns mined from historical data. Their returns stem from market participants’ behavioral inertia, information asymmetry, and liquidity frictions. They are invaluable practice materials for many quants in their early learning stages.
In KuangTi Quant’s course “Factor Analysis and Machine Learning Strategies,” we also focus on explaining the construction principles of Alpha101 factors.
At this point, some readers might ask: Since the 101 factors are already public and widely known, won’t their returns diminish? Won’t these factors become ineffective?
This is reasonable but not entirely accurate. On one hand, as Mr. Wang stated, when he studied Alpha101, he localized these factors rather than copying them directly. After modification, these factors may still generate excess returns in the China A-share soil.
On the other hand, you argue that widespread use leads to factor decay. Conversely, when everyone believes a factor is ineffective and stops using it, might it become effective again? This is the source of strategy cyclicality. Furthermore, just as waste can be recycled, old signals can still yield new value.
Each factor has its suitable scenario; its effectiveness depends on specific market environments, asset attributes, or time windows.
Through scenario-based attribution, we can identify the specific market environments where factors generate excess returns, thereby achieving precise timing and allocation of factors.
We can also structurally decompose old factors, reducing them to linear or nonlinear combinations of basic variables. By re-examining the weighted logic and internal assumptions of these basic variables, we can optimize variable weights or reconstruct combination methods. Without introducing new data sources, we can uncover the Alpha value hidden within old signals, achieving endogenous evolution and iteration of strategies.
What Is the Difference Between End-to-End and Non-End-to-End?
What is “end-to-end” (End-to-End)? It is a concept in machine learning, corresponding to “non-end-to-end.”
In the strategy construction and execution framework of quantitative investing, the core difference between end-to-end and non-end-to-end strategies lies in whether the transformation path from raw input data to final trading decisions passes through explicitly decomposed manual intermediate steps.
Non-end-to-end strategies follow a manually dominated step-by-step logic. They first require manually screening effective factors based on financial theory and historical backtests. Then, factor data is processed through standardization, neutralization, etc. Subsequently, humans set factor weights and build scoring systems. Finally, investment portfolios are generated based on comprehensive stock scores. Every step in the entire process is interpretable and traceable.
End-to-end strategies allow models to autonomously learn potential correlations and patterns in data, without manually presetting rules for factor screening or weight allocation. This integrated mode directly outputs stock buy/sell signals or asset allocation combinations.
In simple terms, end-to-end strategies delegate decision-making power to the model for autonomous mining, while non-end-to-end strategies are dominated by manual rules in constructing strategy logic. This is why we describe this process as an untraceable “black box.”
Daily Prestigious University
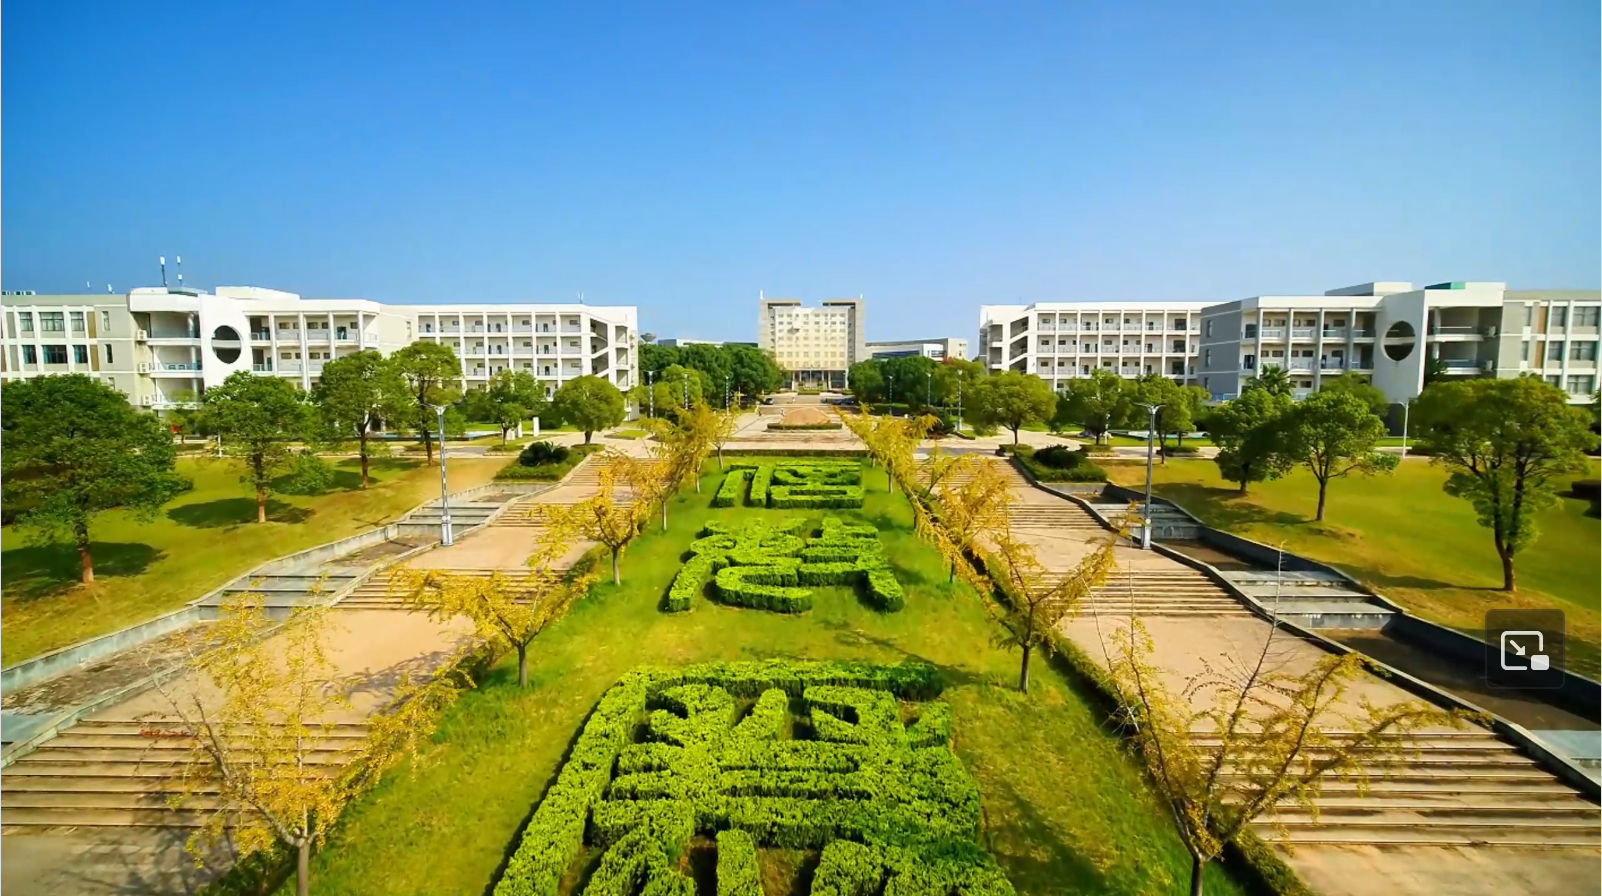
The prestigious university introduced today is Mr. Wang Yiping’s alma mater, Jiangxi University of Finance and Economics (JUFE). Although its fame may not rival Tsinghua, Peking University, Fudan, or Shanghai Jiao Tong University, its “alumni power” in the financial and venture capital circles is惊人 (staggering). Today, instead of guessing the university name, let’s guess these heavyweight figures who graduated from JUFE:
- The “Watcher” of Capital Markets: A renowned Chinese economist and former vice president of Renmin University of China, known for his profound insights into capital markets and outspoken nature.
- The “Logic Controller” of a 10-Billion RMB Private Equity Firm: The protagonist of our article. He achieved a 50-fold leap in principal during his master’s studies and now leads one of China’s top quantitative private equity firms.
- The “Entrepreneurial Goddess” of New Tea Drinks: She successfully created the first listed new tea drink brand (Nayuki Tea), turning “milk tea” into a lifestyle.
- The “Evergreen Tree” of Industry and Investment: He founded Kerry Group, with profound achievements in healthcare, mining, finance, and other fields.
Do you know any other hidden-gem alumni from JUFE? Feel free to leave a comment below!