
HSBC & IBM: Quantum Computing Reshapes Bond Trading
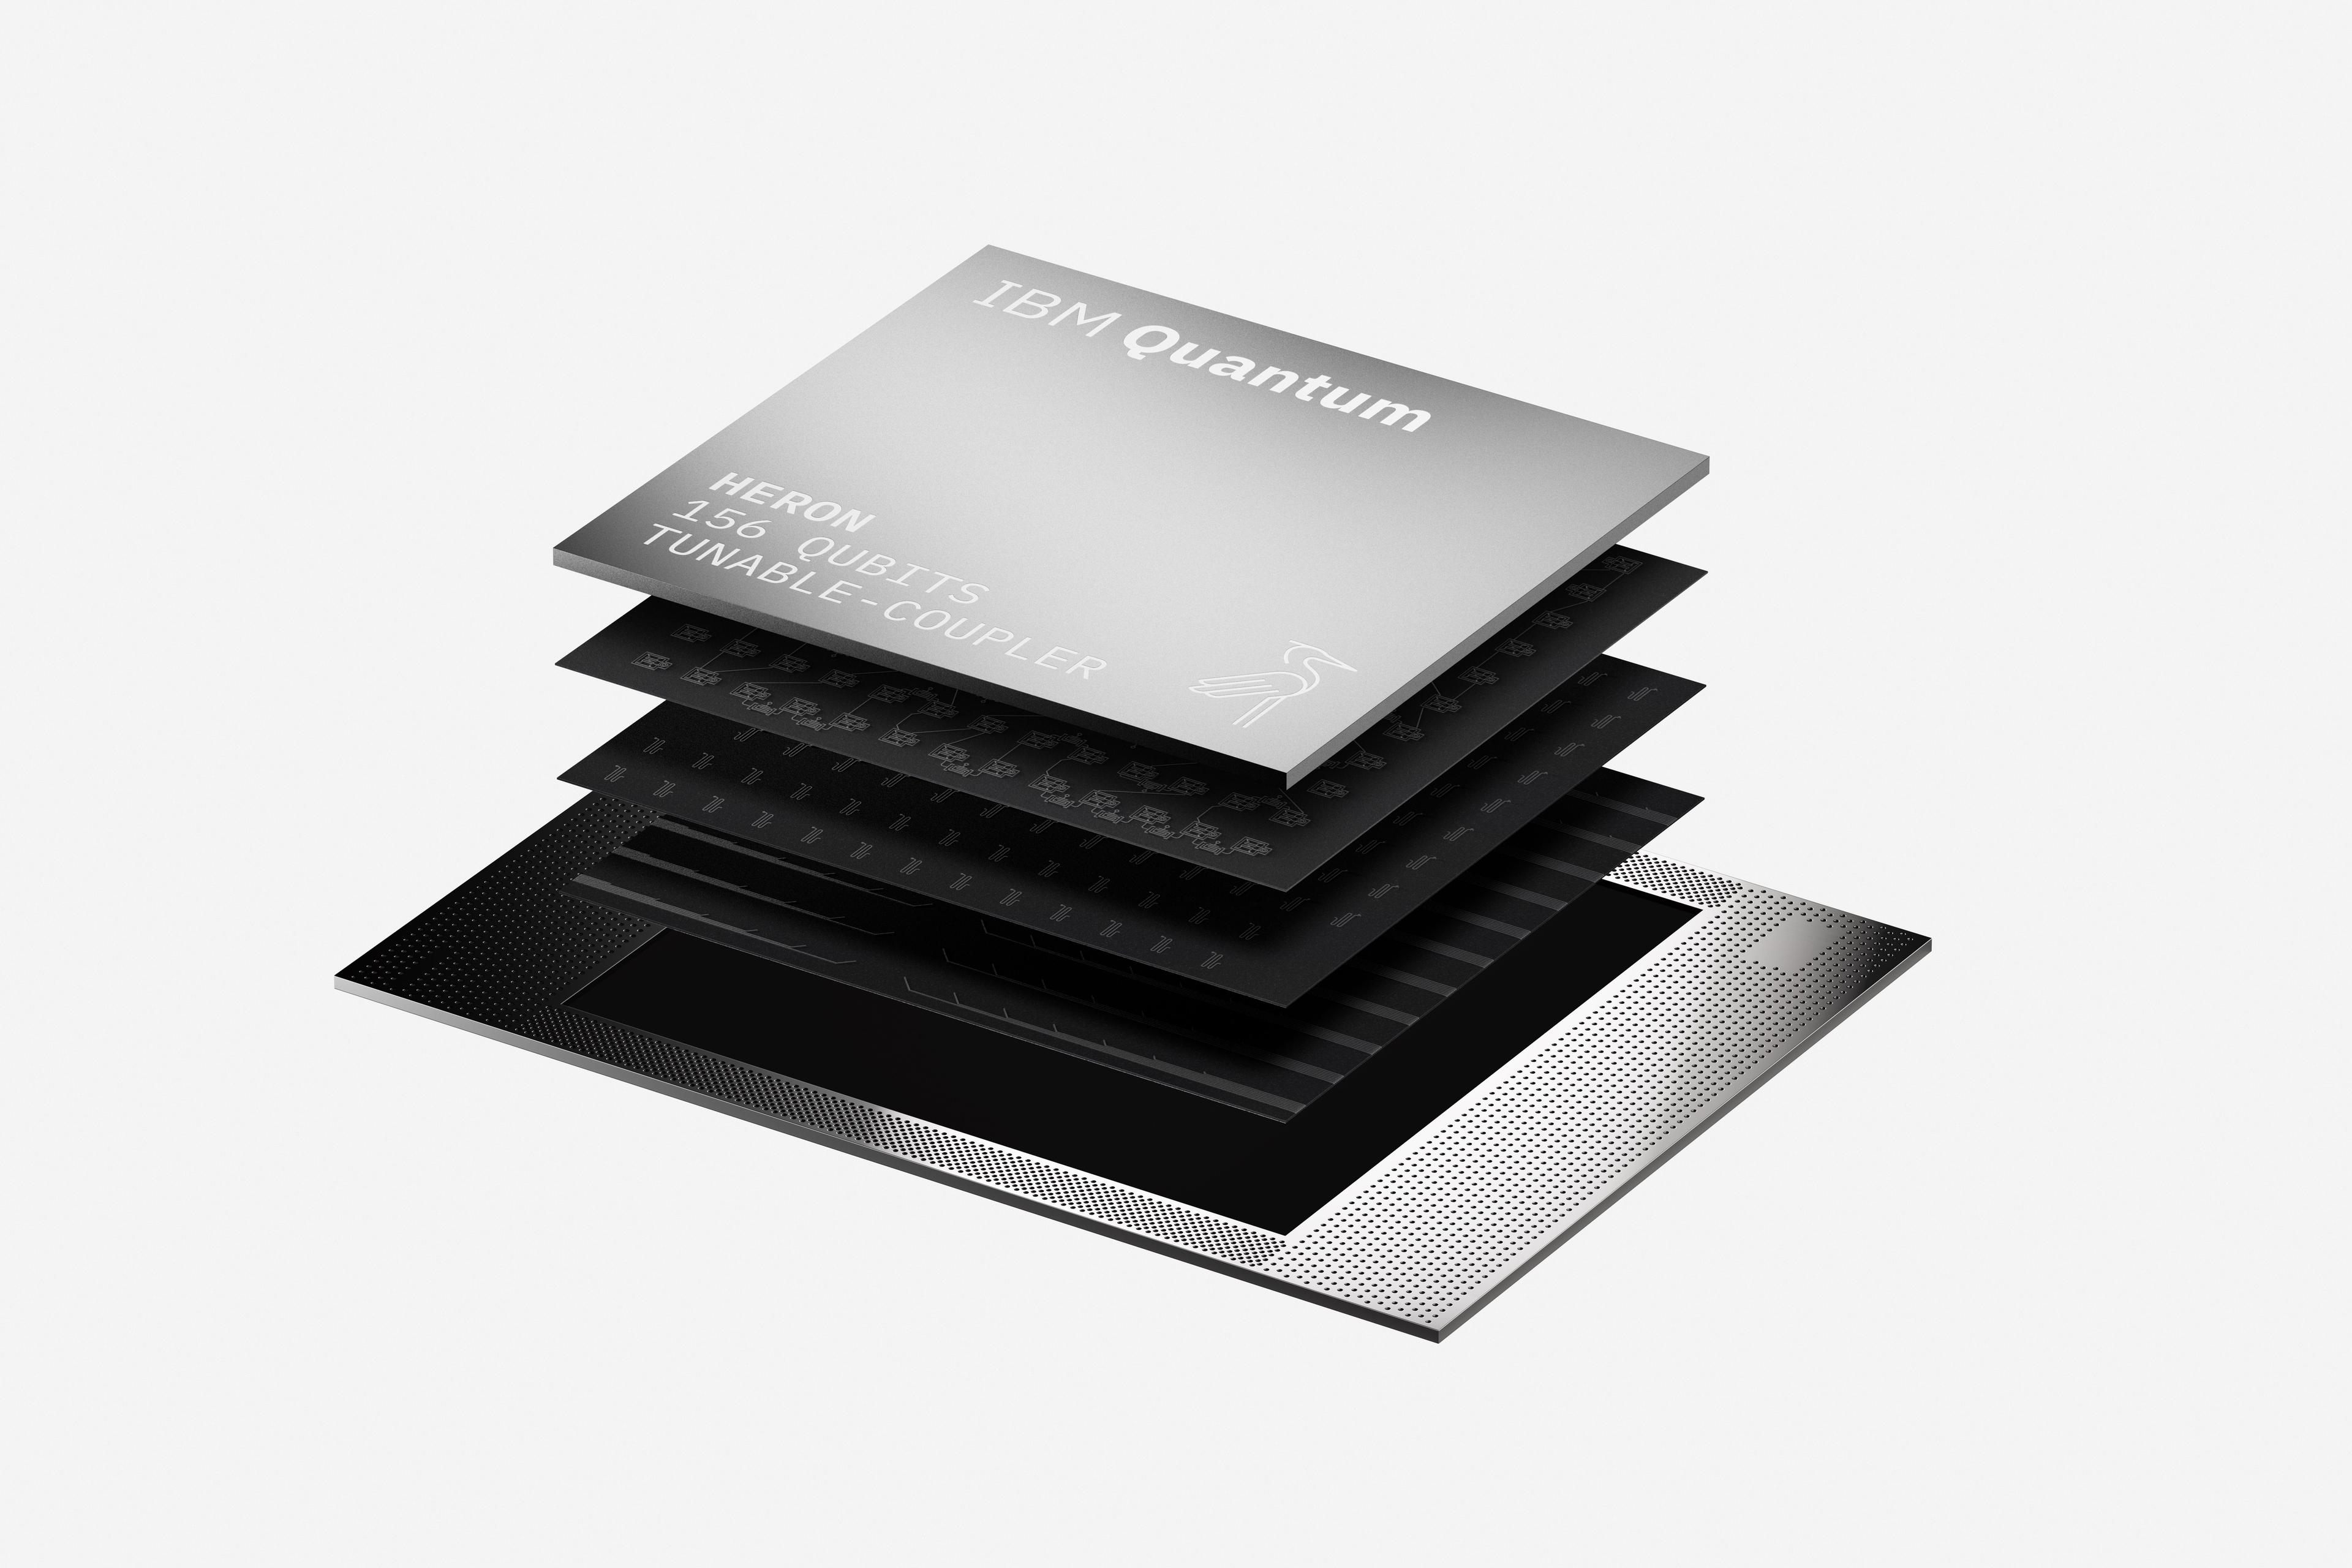 Image source: IBM website
HSBC’s quantum computing breakthrough may define the future of Wall Street.
On September 25, amidst the sleek, high-rise towers of Canary Wharf, London’s vibrant financial hub, HSBC ignited a transformation in quantitative trading.
In collaboration with IBM, the bank unveiled the world’s first known quantum-enabled algorithmic trading demonstration. Leveraging a cloud-based quantum processor, the system processed real-world data from Europe’s €12 trillion corporate bond market.
The result—a 34% improvement in the accuracy of trade-execution probability predictions—has triggered a ripple effect across global markets. This signals a future where quantum computing could reshape Wall Street, just as mainframe computers revolutionized finance in the 1960s and 70s. Quantum computing is poised to bring disruptive change to the financial sector.
Philip Intallura, HSBC’s Group Quantum Technology Lead, stated: “This is a groundbreaking global first in bond trading. It provides a tangible case study demonstrating how current quantum computers can scale to solve real-world business problems and deliver competitive advantages—an advantage that will continue to expand as quantum hardware evolves.”
This milestone arrives at a critical juncture for Wall Street, where fleeting advantages in speed, accuracy, and insight determine success or failure.
While quantum computing has long been hailed as the next frontier, it was often dismissed as hype lacking practical applications. Now, it offers empirical proof of its value in finance.
This development may not only reshape bond trading but also the entire architecture of quantitative finance, echoing the transformative role of mainframes in the 1960s and 70s. Back then, IBM’s bulky machines revolutionized stock exchanges by automating data processing and supporting early algorithmic strategies. Today, as IBM’s Heron quantum processors begin tackling problems intractable for classical computers, history may be rhyming, if not repeating itself.
It is worth noting that IBM, once a tech giant, has recently had a quieter presence, sometimes evoking a sense of decline. Yet, this century-old institution often operates in the shadows, quietly preparing major breakthroughs. They seem to possess an indestructible gene.
01
To understand the significance of HSBC and IBM’s achievement, consider the problem it addresses: the European over-the-counter (OTC) corporate bond market. This €12 trillion market exhibits uneven liquidity, where pricing is both a science and an art.
In the high-stakes arena of OTC corporate bond algorithmic trading, dealers like HSBC face a daunting challenge: they must quote prices that win trades in response to Requests for Quotes (RFQ) while minimizing risk.
The key to a successful trade lies in predicting the “execution probability”—the likelihood that a specific quote will result in a transaction within a millisecond-competitive, auction-like environment.
Before quantum computing, this process relied on classical algorithms to process complex, noisy market data. Traders integrated real-time data streams (including bid-ask spreads, average trade sizes of €1–5 million, and volatility indicators like the MOVE index) alongside client-specific data (such as historical acceptance rates).
This workflow was supported by classical models such as Support Vector Machines (SVM) and Extreme Gradient Boosting (XGBoost). SVMs classify trade outcomes (executed or not) by mapping market features to decision boundaries, while gradient boosting models excel at capturing non-linear patterns in sparse datasets, recalibrating hourly to reflect market changes.
A typical workflow begins with an RFQ: for instance, a client requests a quote for a 5-year investment-grade bond. The algorithm retrieves market data from platforms like Tradeweb, integrates it with HSBC’s trading history, and predicts the optimal quote, balancing quote competitiveness against inventory costs.
However, as dataset complexity grows exponentially, these classical models struggle—burdened by the “curse of dimensionality” and insufficient OTC market liquidity, leading to suboptimal predictions and missed opportunities.
Enter quantum computing. HSBC’s demonstration leverages IBM’s Heron processor, introducing quantum kernel estimation—a hybrid method that maps noisy market data to a higher-dimensional space using superposition (a core quantum principle allowing simultaneous exploration of vast feature combinations).
Unlike classical models that struggle to capture complex correlations in OTC markets, quantum kernel methods excel at uncovering hidden patterns, ultimately boosting execution probability prediction accuracy by 34%. As Philip Intallura noted, “This is a groundbreaking global first in bond trading.”
That 34% increase is more than a number; it is a harbinger.
In bond trading, margins are razor-thin, yet annual trading volumes exceed trillions of dollars. Such an advantage implies higher liquidity, tighter spreads, and greater profitability.
02
The reaction was swift.
On X (formerly Twitter), Giuseppe Paleologo, a quant expert who worked at Millennium and Citadel and author of Elements of Quantitative Investing, called it an “excellent way to start the day,” sharing HSBC’s press release and sparking discussions among thousands of followers.
Fintech influencer Dr. Efi Pylarinou praised it as a “quantum breakthrough,” highlighting its potential to “improve profit margins and enhance liquidity.”
Of course, cryptocurrency enthusiasts were particularly attentive: previously, predictions suggested that once quantum computing breaks through, it would hit the weak spot of cryptocurrencies.
To understand why this feels like a turning point, we must look back to the 1960s and 70s, when computing first penetrated finance.
Mainframe computers, represented by IBM’s System/360 launched in 1964, were behemoths designed to handle massive enterprise datasets. In stock markets, they automated back-office tasks like account reconciliation and supported early programmatic trading—executing orders bundled according to predefined rules.
By the 1970s, as exchanges like the NYSE struggled to manage surging trading volumes following the bull market of the 1960s, mainframes became indispensable. They processed large-scale data, reduced errors, and shortened settlement times from days to hours.
This era marked the infancy of quantitative trading: firms used computers for statistical arbitrage, identifying mispricings between assets. Subsequently, Wall Street began investing heavily in technology, recognizing that computing power equated to competitive advantage.
People often ask, what is the social value of quantitative trading? Indeed, quant trading is often viewed as pure speculation.
Yet, looking back at history, we see that it once nurtured and drove the development of computer technology, just as gaming has driven artificial intelligence.
Today, the parallels between quantum computing and mainframes are striking. Just as mainframes found their first killer application in the data-intensive demands of finance, quantum processors excel at optimization problems that classical methods cannot solve.
HSBC’s experiment reflects this historical shift: quantum computing does not replace humans or traditional systems overnight but enhances their performance when complexity peaks. Just as minicomputers proliferated alongside mainframes in the 1970s, cloud-based quantum computing stacks like IBM’s Qiskit make this technology accessible, potentially accelerating its adoption.
History shows that once the financial industry embraces a technology, investment surges—IBM’s quantum orders are approaching $1 billion, with the market size projected to reach $97 billion by 2035.
03
Why does quantum computing prevail? Because it solves the “curse of dimensionality,” where classical computational costs grow exponentially.
Delving into the technical fusion, the core challenge of HSBC’s demonstration lies in processing “noisy” data—market signals obscured by volatility, incomplete information, and interdependencies. Classical machine learning models like SVMs map data to find decision boundaries but scale poorly in dimensions.
Quantum kernel estimation disrupts this status quo: qubits in superposition can simultaneously explore vast solution spaces, estimating kernels (similarity measures) more efficiently. In the bond domain, this means better identification of patterns in quote responses and more precise execution predictions.
This hybrid setup—quantum computing for kernel estimation and classical computing for optimization—delivers superior results without requiring fault-tolerant quantum hardware, which remains years away.
This is not unique to bonds. The power of quantum technology extends to various subfields of quantitative finance, promising disruptive advances in areas constrained by traditional techniques. For example, in portfolio optimization, quantum algorithms like the Quantum Approximate Optimization Algorithm (QAOA) can handle the combinatorial explosion of asset allocation, incorporating constraints such as risk tolerance and correlation faster than traditional solvers.
A 2024 arXiv paper on quantum machine learning highlighted applications in this field, noting its potential to enhance returns in multi-asset portfolios.
Risk management will also benefit: Monte Carlo simulations, used to model tail risks in Value at Risk (VaR) calculations, are computationally intensive. As noted in the Bank for International Settlements (BIS) report on quantum opportunities in finance, quantum amplitude estimation accelerates these simulations by quadratically reducing the required sample size.
For derivatives pricing (options, swaps, and exotic bonds), quantum technology could revolutionize extended Black-Scholes models, enabling real-time pricing of complex path-dependent instruments. A 2025 Springer review emphasized quantum advantages in these areas, potentially reducing computation time from hours to minutes.
04
Challenges remain, however. Quantum systems are still error-prone, and scaling to fault tolerance requires years of effort. Quantum is not magic—poor data and flawed modeling will still degrade performance.
Regulatory hurdles also exist: how to audit the “black box” decisions of quantum models? Moreover, from an ethical standpoint, widening technological gaps may exacerbate market inequality, favoring well-capitalized firms like HSBC.
Nevertheless, the momentum of quantum computing is undeniable. IBM’s stock surged 5% following the announcement, as investors believe that if IBM successfully commercializes this technology, it will dominate the future multi-trillion-dollar market. Competitors like JPMorgan Chase are already exploring similar derivatives and optimization algorithms.
If the 1970s taught us anything, it is that finance drives technological innovation. Mainframes originated from bank ledgers; the breakthrough in bond trading prediction via quantum computing may redefine Wall Street’s DNA.